The IRS raised the mileage rate to 76¢ mid-year. Here's what changes for drivers.
The IRS almost never touches the standard mileage rate mid-year. This summer it did: for business miles driven on or after July 1, 2026, the rate is 76 cents per mile, up from 72.5 cents for the first half of the year. The IRS cited fuel prices. For gig drivers it means a bigger deduction on every mile since July, a mileage log that now has to know what month it is, and a cost floor that just moved up.
What changed
The IRS announced the increase on July 13, effective retroactively to July 1. The business rate went from 72.5 to 76 cents; the medical and moving rate from 20.5 to 23.5 cents; the charitable rate stayed at 14 cents, which is set by statute. The last mid-year adjustment was in 2022, for the same reason — fuel. Nothing about the deduction's rules changed, only the number, and only for the second half of the year.
What it means for you
Every mile since July is worth more. A thousand logged business miles deducted $725 in the spring and deducts $760 now. A full-time driver covering 7,500 miles in the second half of the year picks up roughly $260 of additional deduction — for doing nothing differently except logging.
Your log now has two halves. 2026 miles get computed at two rates depending on the date they were driven. An annual total is no longer enough — you need first-half miles and second-half miles as separate numbers, which a dated log gives you and a reconstructed one doesn't (what an audit-proof log looks like).
Your cost floor moved up. The rate is the IRS's estimate of what a mile costs to drive — fuel, wear, insurance, depreciation. If your per-mile minimum was set against 72.5 cents, it's 3.5 cents too low. An offer at $0.90 a mile left 17 cents for your time in June; at today's rate it leaves 14 (how to spot the ones worth declining).
It lowers your September 15 payment, a little. The Q3 estimated payment covers June through August (the five-week plan). Two of those three months are at the higher rate, so net profit for the window is lower than it looks at 72.5 cents — recompute before you schedule the payment rather than after.
Standard mileage got a little harder to beat. Drivers on the fence between the standard rate and actual expenses just saw the standard side get 5% more generous for half the year. If you're in an ordinary car doing ordinary miles, the case for the simpler method got stronger. If you switched to actual expenses earlier this year, the choice is generally locked for that vehicle — ask a pro before assuming you can flip back.
What didn't change
Which miles count, what a log has to contain, and the no-double-dipping rule are all exactly as they were. Commuting still doesn't count; tolls and parking still stack on top of the rate; gas and repairs are still inside it. And the platforms' own mileage estimates still undercount the real thing — they miss the drive to your first pickup and often the drive home. A 3.5-cent raise on miles you didn't log is worth nothing.
Rule of thumb: raise your per-mile floor by a nickel, and make sure every mile since July 1 has a date on it. The first protects your hourly; the second protects the deduction.
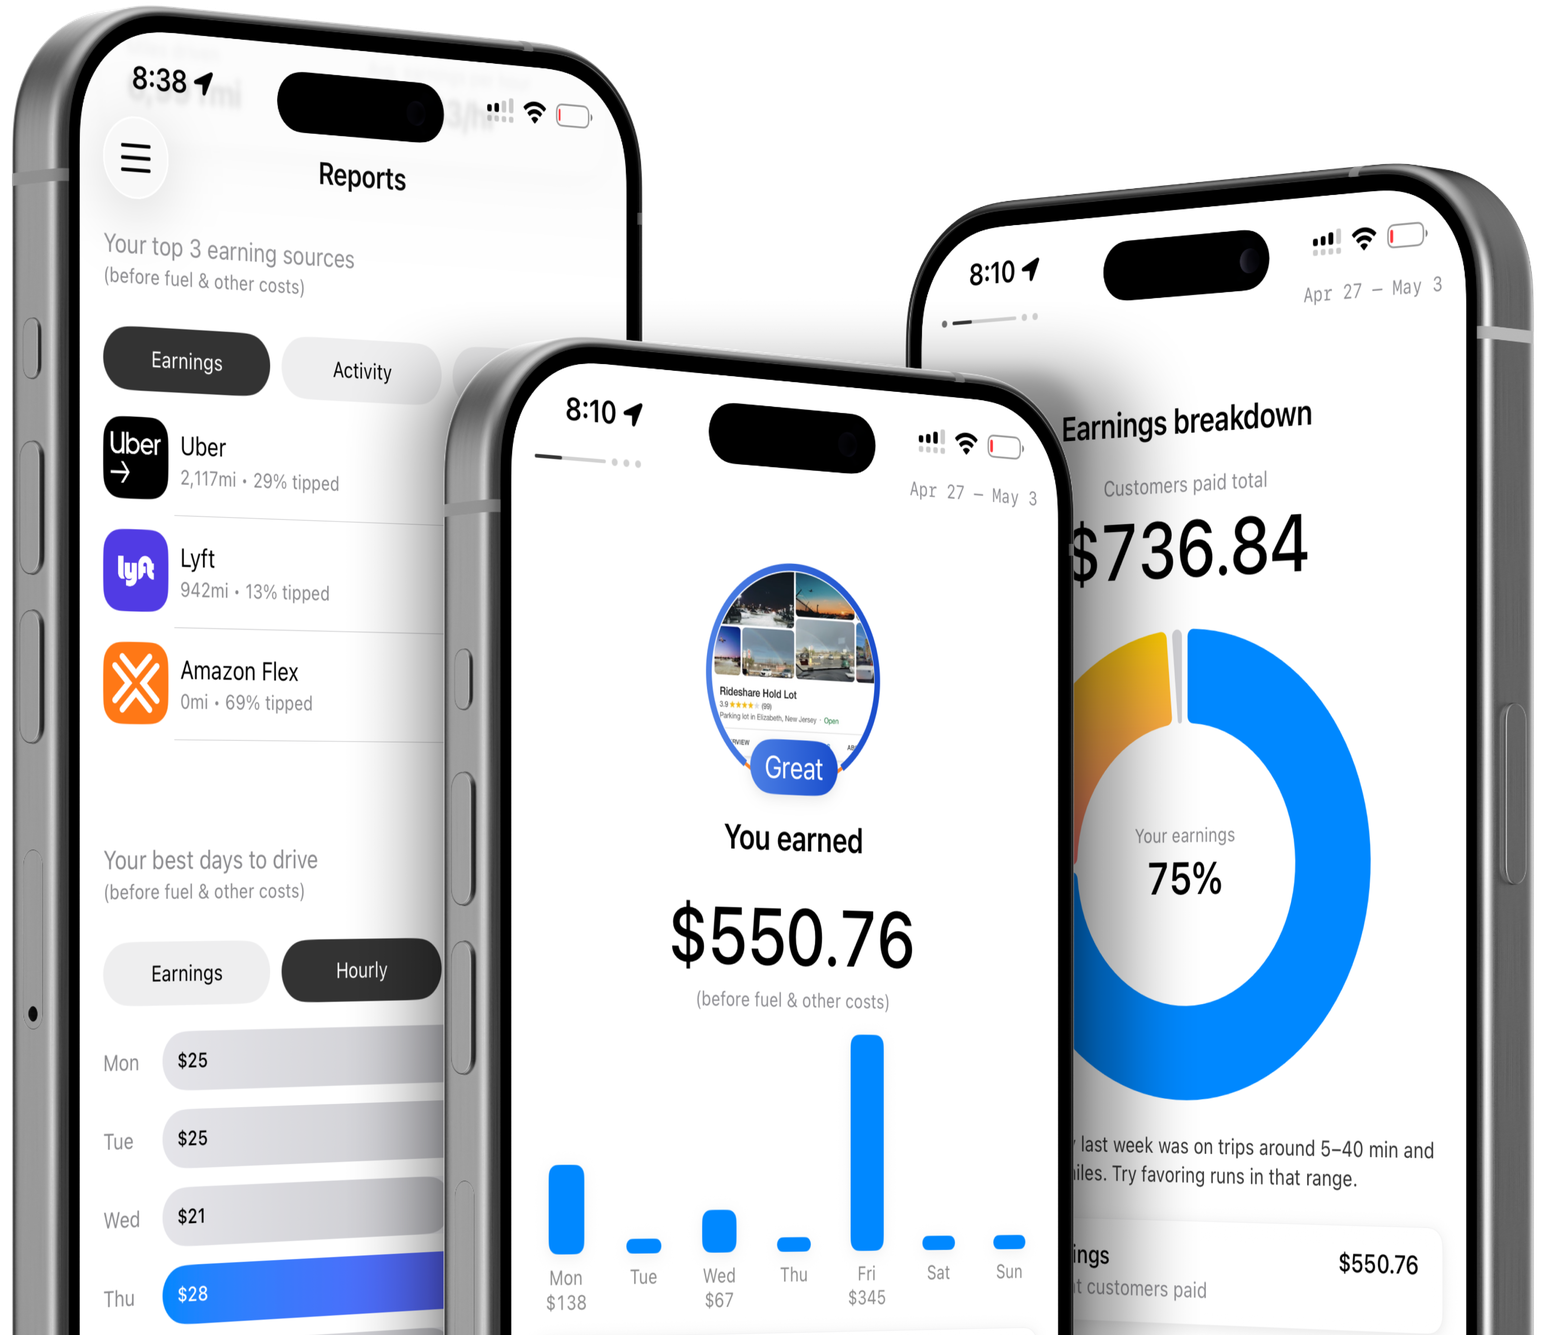
Where GigReal fits: every mile in your log is timestamped, so the split year is already split — first-half and second-half miles are one date filter apart in the tax report, and the net-profit number your quarterly payment needs reflects the rate in effect when you drove.
General information, not tax advice. Rates and rules are the IRS's and can change; leased vehicles, mixed use, and method switches have their own rules — confirm your situation with a tax professional or IRS.gov.